

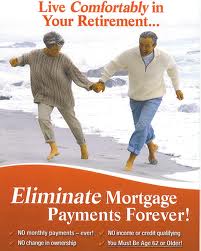
 Many of us have seen the slick advertisements on television for reverse mortgages. An actor who is popular with our seniors will advocate the advertiser’s reverse mortgage program as a way to tap home equity and enjoy the “good life”, the long awaited vacation or purchase of a new car or boat. However, the reality of reverse mortgages can be quite contrary to these advertisements.
A reverse mortgage is a home equity mortgage program only available to homeowners over the age of 62. These mortgages are insured by the Federal Housing Administration, a division of the Department of Housing and Urban Development. A portion of the home equity is made available for the loan, which proceeds are distributed in several ways. The homeowner can receive the proceeds in (1) monthly installments for so long as he lives in the house, (2) monthly installments for a set period of years or (3) as a line of credit that can be used as needed. Unlike a conventional mortgage, a reverse mortgage does not need to be paid until the borrower dies or no longer occupies the home as his primary residence. Not needing to make a monthly payment while having funds available for home improvements, medical expenses or other retirement needs is obviously highly attractive to seniors.
However, this author wishes to demonstrate particular concerns with respect to reverse mortgages that have actually been experienced by some of her clients. A reverse mortgage borrower must be at least 62 years of age. Let us consider a married couple that jointly owns their home, the wife is 57 and the husband is 63, meaning that only the husband can become the borrower. If the husband dies first, the surviving widow will be unlikely to repay the loan which is now due in full (without selling the house in which she may wish to continue living). The primary residence requirement may also cause difficulties. If the borrower needs to live in a residential care facility indefinitely due to medical issues, the loan will be due in full and the borrower will be unlikely to have the funds to repay. Of course, once the borrower dies, triggering the due in full provision, the lender may not patiently await receipt of the house sale proceeds needed to repay the loan and may commence a foreclosure or other legal proceeding. After the financial crisis of 2008, homes have not sold as readily as in the past, making it more difficult for survivors to sell homes to satisfy the reverse mortgage lender’s schedule. Further, with home values having dropped in recent years, there may be insufficient proceeds from the house sale to pay the loan, making the balance due from the estate.
 New York City’s population density inherently gives rise to noise complaints by cooperative neighbors.
 The resurging real estate market brings with it the real estate “flipper”. A flipper is a person or entity that purchases property with the goal of renovating it for a quick sale at a substantial profit. The flipper never intends to occupy the property in the neighborhood. Recently,
 Our readers may be aware of an
 A
 Real estate transactions commonly involve the inclusion of title insurance policies. For the purposes of this blog post, we will be discussing title insurance obtained when a person purchases a house. Title insurance is a unique type of insurance, in that the events that are to be covered have already occurred. For instance, an automobile policy covers loss resulting from an accident that could happen after the policy is bound. On the other hand, title insurance covers acts that have already happened but not discovered prior to closing, such as a fraudulent deed in the chain of title.
 Our firm often fields inquiries from clients regarding residential lease situations. One common question relates to the right to renew an existing lease. This blog post will explain certain conditions which may apply to the renewal of a lease after it expires.
 Our readers who follow politics know that members of Congress have battled in recent years with respect to revisions to the tax law. Specifically, estate, gift, and income taxes have been subject to adjustments. The purpose of this blog post is not to describe the